


Industry Odisha Bureau, Oct 07: India has added solar capacity at record speed. Yet its factories make far more modules than cells. US tariffs, midday power gluts and costlier batteries are now testing the energy boom.
India’s solar build-out has moved faster than the systems around it. The harder problems now lie upstream in factories and downstream on the grid. Three gaps stand out: missing cells, midday surpluses and scarce storage.
A decade of rapid growth
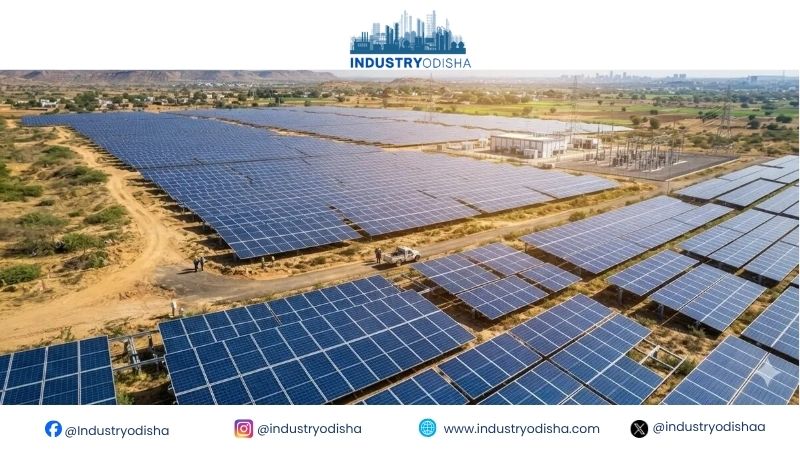
Solar capacity rose from under 3 GW in 2014 to 168 GW by August. In FY26 alone, India installed about 44.6 GW, nearly double the previous year. Utility-scale additions rose from 16.9 GW to 34.8 GW, according to JMK Research. Falling tariffs, renewable mandates for discoms and corporate demand drove the rush. Tariffs fell from about ₹12 a unit in 2010 to below ₹2.50.
Modules race ahead
Manufacturing grew just as quickly, but unevenly. In January–June 2026, module capacity grew 50.6 GW; cells grew just 9.7 GW. Per gigawatt, a cell plant costs roughly four times as much as a module line. It also takes nearly twice as long to build. Capital naturally chased the easier option.
Against baseline demand of 65 GW, module capacity stands at 215 GW. That leaves a 150 GW surplus, with many factories underused and margins thin. Upstream, the picture reverses. Cell capacity of 40 GW falls 25 GW short. Wafer-ingot capacity is just 6 GW, and polysilicon capacity is zero.
Standalone assemblers still import cells, largely from China. Cell and module imports rose 18% in the first half of 2026. Since 1 June, discoms and government-backed projects must use approved Indian cells.
Tariffs shut a key outlet
Exports once absorbed the excess. At its peak, the US took about half of India’s module output. In September, Washington finalised anti-dumping and countervailing duties on Indian solar cells and modules. US tariffs are only part of the problem. US imports had already halved in 2025 and fell again in early 2026. Tax credits helped American factories build about 70 GW of module capacity. US buyers now want cells, which India cannot spare.
Too much power at noon
The second bottleneck sits on the grid. Solar output peaks at midday, but India’s demand mostly peaks in the evening. Distributed solar, 16.3 GW or 36% of FY26 additions, adds to the noon surge. Rooftops alone contributed 8.7 GW, aided by schemes such as PM Surya Ghar.
On 5 April, afternoon prices on the IEX Real-Time Market fell to almost zero. When supply outruns demand, grid operators order solar plants to cut output. Coal plants cannot run below a technical minimum, so solar gives way. Inter-state curtailment reached 470 GWh in the January–March quarter. Each cut costs developers revenue.
Batteries lag the pipeline
Battery storage could shift midday surplus into the evening. Storage-linked tenders rose from about 5% to nearly 40% of auctioned capacity in two years. Yet India commissioned only about 2.6 GWh of storage in FY26. Some 45–50 GWh is due over the next two years.
Developers bid low in 2024 and 2025, expecting battery prices to keep falling. Instead, geopolitical tensions and material shortages lifted prices by about a third in 2026. Lithium carbonate futures nearly tripled to about 192,000 yuan a tonne by May 2026. Crisil Ratings estimates 12 GWh under construction will earn less than investors expect. Another 8–9 GWh risks delay.
A costlier next phase
India’s first solar task was building cheap generation at speed. The next task is more capital-intensive. It requires cells, wafers, grid flexibility and storage. India’s goal of 500 GW non-fossil capacity by 2030 hinges on closing these gaps.
